


Pradhan Mantri Awas Yojana Urban (PMAY 2.0)



Experience the all-new Kotak Netbanking
Simpler, smarter & more intuitive than ever before


Quick Help
Frequently Asked Questions
Show More
For Kotak Bank Customers
For Kotak811 Customers
Experience the all-new Kotak Netbanking Lite
Simpler, smarter & more intuitive than ever before. Now accessible on your mobile phone!
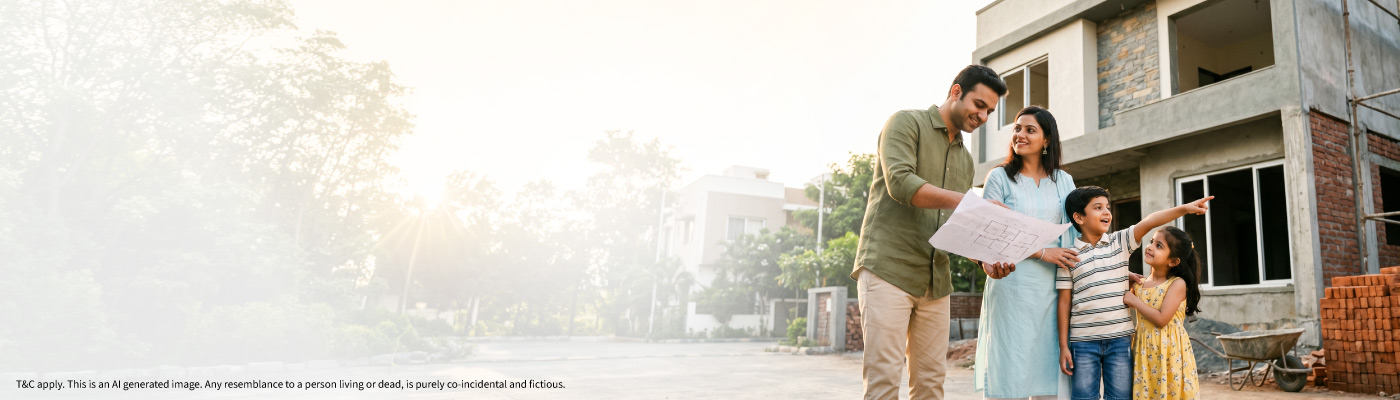
Pradhan Mantri Awas Yojana Urban (PMAY-U) 2.0 is the flagship scheme of the Government of India for urban housing, which is aimed at providing eligible families with an opportunity to buy, construct, or rent an affordable house in cities. The scheme is continued with the overall objective of PMAY housing for all by providing assistance to households belonging to the economically weaker section (EWS), lower-income group (LIG), and middle-income group (MIG) categories.
At Kotak Mahindra Bank, our home loan specialists are available to guide you in PMAY-U 2.0 applications.
One of the benefits of PMAY-U 2.0 is the Interest Subsidy Scheme (ISS). Under this scheme, eligible beneficiaries can receive a subsidy of ₹ 1.80 Lakh on their Home Loan. The subsidy is directly credited to the loan account of the beneficiary.
For PMAY-U 2.0 scheme eligibility, a family must meet certain criteria with respect to income, ownership and whether they own a permanent house or not. The most important eligibility requirements are:
PMAY-U 2.0 also lays emphasis on women's property ownership. As per the scheme, homes will be registered in the name of the female head of the family or jointly with her husband. The intent of this provision is to promote women home ownership and secure their financial future.
This condition is waived only if there is no adult female in the family. The home can be registered in the name of the widower, unmarried person, or transgender person.
No Prior Benefits:
PMAY-U 2.0 does not apply to families allotted a house under any Central, State, or local government scheme for housing for the last 20 years.
Sale of Property:
During the lock-in period, if the property is sold, the original subsidy is not transferable. Only one subsidy is granted for an eligible property.
Balance Transfers on Loans:
If the Home Loan is transferred to another financial institution, the subsidy cannot be claimed after the transfer. The beneficiary must claim the subsidy from the original lender.
Non-Performing Assets (NPA)
The loan becomes NPA when the borrower/beneficiary defaults in repayment.
The above-mentioned exclusions may not be comprehensive, and the decision to grant benefits under PMAY-U 2.0 rests with NHB.
Kotak Mahindra Bank is an authorized Primary Lending Institution (PLI) under PMAY-U 2.0, enabling eligible customers to apply for a home loan and claim the ISS subsidy through a single, guided process.
With attractive interest rates, flexible repayment options, and a hassle-free loan application process, Kotak Mahindra Bank can help you make the most of the PMAY-U 2.0 scheme and ensure that you can own your dream home without any hassles.
The above details are extracts of the PMAY-U 2.0 scheme. Borrowers are requested to go through the entire scheme issued/amended by the Ministry of Housing and Urban Affairs (MoHUA) from time to time.
Click here for more information.
EWS, LIG, and MIG households can apply if they do not own a pucca house anywhere in India. The income slab and property conditions must also match the scheme requirements.
Under ISS, eligible beneficiaries can receive an interest subsidy of 4% per annum on the first ₹8 lakh of the home loan, with a maximum benefit of ₹1.80 lakh.
The property is to be registered in the name of the female head of the household or jointly with her spouse. Relaxation of which is to be provided where no adult female member exists.
Yes. The official PMAY-U 2.0 portal provides an application and beneficiary tracking facility, including status check post submission.
If you are an NRI and are looking for a Home Loan, Kotak provides you just that. Check out our NRI Home Loans section.
To ensure timely Home Loan repayments and ensure extended benefits, open a Savings Account from Kotak.
You can avail a Personal Loan from Kotak with the same documentation to meet unexpected expenses.
If you are looking for renovating your home, you can do so by taking Kotak’s Home Improvement Loans
You can pay off any existing balance of Home Loan using Kotak’s Home Loan Balance Transfer at a lower rate of interest.
Disclaimer (Things you should know):
Information updated as of July May 2026. While we strive for accuracy, banking regulations can change. For the most current advice specific to your situation, please contact your relationship manager. Applicable only for fresh loan applications. For loans that have already been disbursed, please contact Customer Support.
Disclaimer - This Article is for information purpose only. The views expressed in this Article do not necessarily constitute the views of Kotak Mahindra Bank Ltd. (“Bank”) or its employees. The Bank makes no warranty of any kind with respect to the completeness or accuracy of the material and articles contained in this Article. The information contained in this Article is sourced from external experts empaneled for the benefit of the customers and it does not constitute legal advice from the Bank. The Bank, its directors, employees and the contributors shall not be responsible for or liable for any damage or loss resulting from or arising due to reliance on or use of any information contained herein.
Latest Comments
Leave a Comment
Comment sent to Admin for review.
Comment was not posted due to some error
Close